Desktop and Hybrid Valuations in Amsterdam: What Changes?
Compare physical, model-based and hybrid valuations in Amsterdam, with the evidence, lender checks and limits that matter before you choose a valuation path.
TL;DR
Choose the physical path when the lender, purpose or property needs an inspection and a full property file. Consider a hybrid path only when the lender permits it for the application and the property fits its conditions. Treat a model-based result as a data-led estimate with its own limits. The word “desktop” appears in older public material; NHG’s current explanation uses “hybrid valuation” for the model-and-remote-review path.
- Physical: a professional visits and inspects the home.
- Model-based: a model calculates from existing data without a property visit.
- Hybrid: data and a model support a value, then an appraiser reviews it remotely.
If the purpose, recipient or timing is still unclear, share your Amsterdam method question so we can help you frame the next step. Keep passports, bank details, contracts and other private documents out of the public form.
Three evidence paths
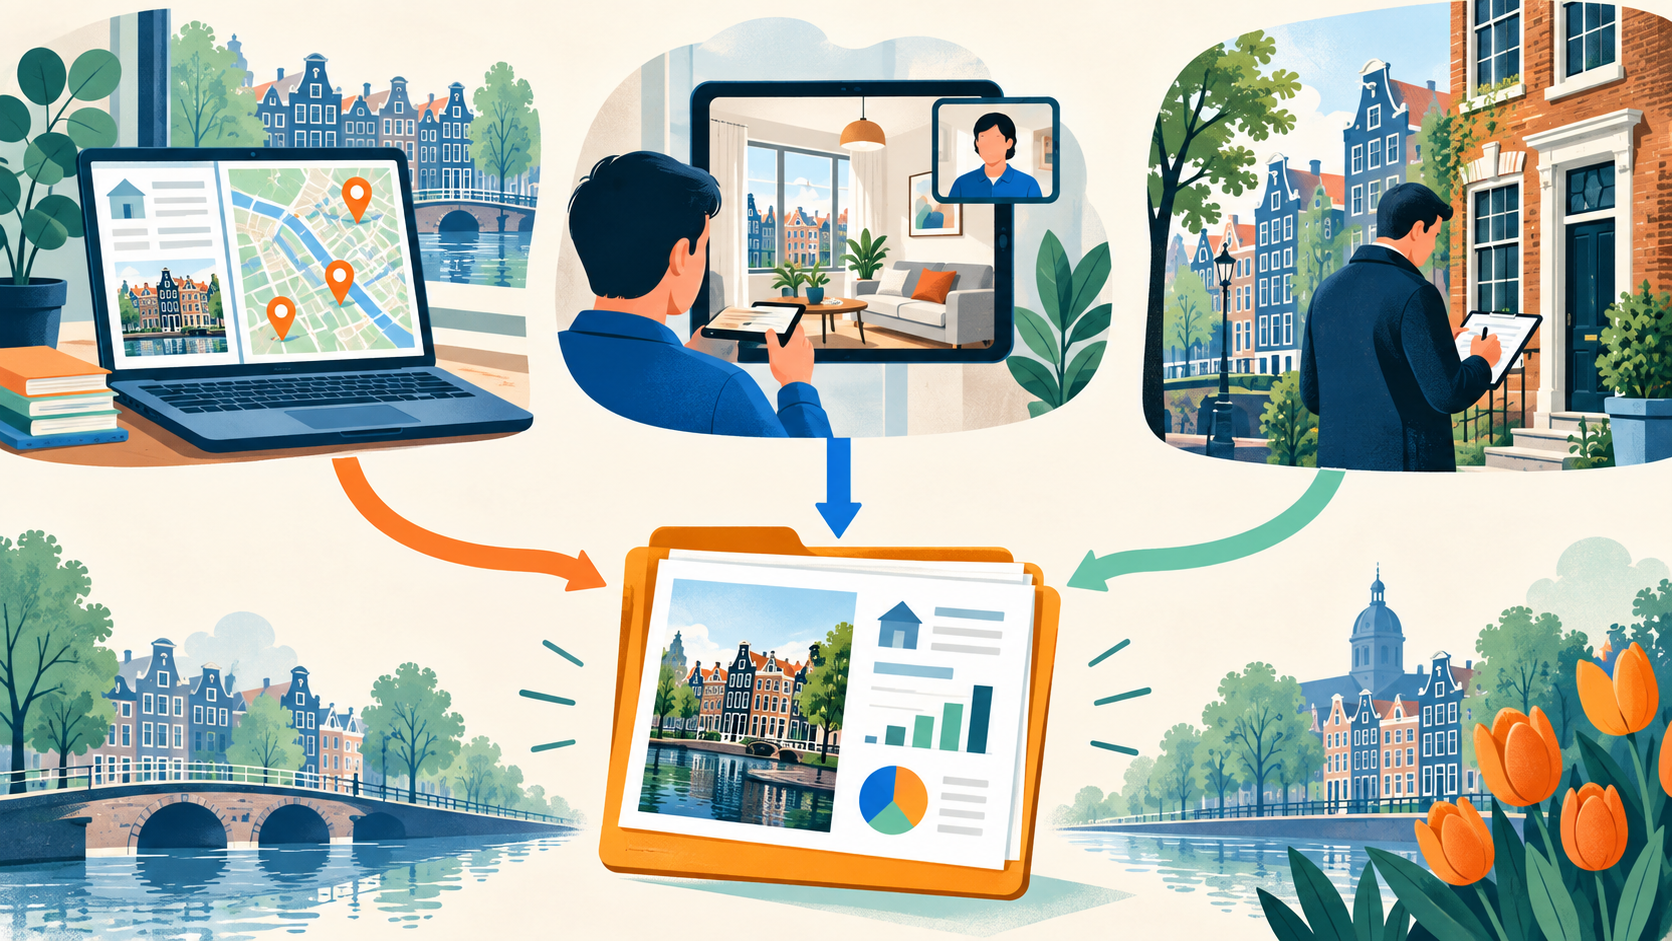
Desktop and hybrid valuations in Amsterdam describe a valuation path where the property may be assessed with data and a model, with a property appraiser reviewing the result remotely. A physical valuation includes a visit and inspection. A model-based valuation uses existing data without an appraiser’s visit. The purpose, property, lender and report conditions decide which path fits.
If the assignment requires a registered professional, keep the signatory’s NRVT registration beside the recipient’s requirements before you compare the report.
Which method fits your Amsterdam file?
Use it if you are:
- arranging a mortgage for an existing Amsterdam home;
- comparing a physical report with a hybrid option;
- refinancing or considering a mortgage change;
- planning work that may change the property question;
- asking whether a remote method fits a home with leasehold, apartment rights or unusual condition.
Questions to settle before choosing a method
When a mortgage file has NHG conditions, the required report checks should be settled before comparing valuation methods. The comparison focuses on the choice between evidence paths.
The method is easier to choose once property valuation in Amsterdam is defined by purpose, recipient and evidence.
A physical visit only makes sense when the valuation process connects purpose, records, inspection and reporting.
Purchase, refinancing, mortgage increase and renovation can follow different rules. When you define the assignment, compare its purpose and recipient with different types of property valuation before you choose the evidence path.
Include the apartment right, VvE material and leasehold records before choosing. A remote method still depends on a complete rights file, including Amsterdam leasehold records.
If the question concerns value after energy improvements, ask whether the lender requires a physical valuation. When an energy question matters, compare the property record with energy-label evidence before you treat the label as valuation evidence.
If you are clarifying what a lender expects, compare your report brief with mortgage valuation questions while keeping the Amsterdam assignment and recipient specific. The location and recipient differ, so confirm the Amsterdam conditions separately.
A physical valuation is the alternative when the lender requires a visit or the property question needs observed facts. A building survey is the alternative when you need detailed defect or repair-cost analysis. A mortgage adviser owns the borrowing question. Method and scope belong in the same quote conversation, and valuation costs in Amsterdam make that comparison concrete.
When a remote method seems suitable, online valuation services in Amsterdam still need a purpose, property type and recipient check.
At-a-glance comparison
Property visit
- Physical
- Yes
- Model-based
- No
- Hybrid
- Remote review
Main evidence
- Physical
- Observed facts and records
- Model-based
- Existing data and model output
- Hybrid
- Data, model output and remote review
Who checks the result?
- Physical
- Appraiser preparing the report
- Model-based
- Model process
- Hybrid
- Appraiser approving the result remotely
File fit
- Physical
- Depends on purpose and recipient
- Model-based
- Limited to permitted uses
- Hybrid
- Depends on current lender conditions
First question
- Physical
- What needs inspection?
- Model-based
- What data exists?
- Hybrid
- Who accepts this path?
The comparison describes evidence paths, not a universal product menu. Ask the recipient before relying on a name such as desktop, model-based or hybrid.
Physical valuation
A physical valuation includes a visit to the home. The professional can observe layout, condition, finish, access, visible installations and surroundings, then consider the records and comparable properties relevant to the assignment. The report states the value opinion, date, assumptions and limitations.
This path suits a file where the lender requires a physical inspection, where the property facts need close observation or where rights and planned work need fuller discussion. It still has a defined scope. A property inspection for valuation is not the same as a structural survey.
Ask:
- Which parts of the home will be inspected?
- Which records should be ready before the visit?
- How will leasehold, apartment rights or planned work enter the file?
- What report form and acceptance review does the recipient need?
Model-based valuation
A model-based valuation uses existing data and a model to estimate a value without a property visit. NHG describes model-based valuation as a distinct form from physical and hybrid valuation. Its usefulness depends on the permitted purpose, property type, available data and recipient conditions.
The model cannot see a changed layout, a hidden defect, an unusual finish or a record that is missing from its inputs. Ask what data the result uses and which property questions remain outside it. A model output should not be treated as a full inspection.
Hybrid valuation
In a hybrid valuation, objective data and an advanced model support a value, and a property appraiser reviews the result remotely. NHG describes hybrid use for certain existing-home mortgage situations, including purchase, refinancing and some quality-improvement cases. Public NHG guidance also states a 90% loan-to-value boundary for the listed use cases and identifies situations where a physical valuation remains needed.
Acceptance is a file question. Ask the lender which product, report, acceptance review and property conditions apply on the date of your application. The fact that a hybrid path exists does not answer whether your lender accepts it for your home.
What changes in the evidence
The three paths change the evidence available to the professional and the way the result is checked:
- Visit: a physical path adds observed property facts.
- Records: every path still depends on the identity, rights and documents in the file.
- Model: a hybrid or model-based path depends on the available data and model conditions.
- Review: a hybrid path adds a remote appraiser review, while the lender still checks acceptance.
- Boundary: none of the paths is a building survey or a mortgage decision.
Six questions before choosing
1. Who is the recipient?
Name the lender or other person who will rely on the report. Ask for the current form and acceptance conditions in writing.
2. What is the purpose?
State whether you need the valuation for a purchase, mortgage, refinancing, sale or another decision. The purpose and recipient decide whether a remote path can answer the question.
3. What is unusual about the property?
Mention leasehold, apartment rights, a monument, an extension, a changed layout, planned work or a visible condition question. Unusual facts can affect which evidence path makes sense.
4. Which records exist?
Gather plans, deeds, leasehold records, VvE material, work specifications, energy-label information and lender instructions where relevant. A remote path still needs a readable file.
5. What date applies?
Record the value date, report date and any age condition. NHG’s physical-report FAQ says the report may be no more than six months old from the value date for that context. Check the current wording with the recipient.
6. What happens if the path is rejected?
Ask whether a physical report can be commissioned and what must be repeated. Put this question beside the deadline so a method choice does not create an avoidable gap.
Four Amsterdam scenarios
Existing home with a standard file
Ask the lender whether a hybrid path is permitted. If the property records, purpose and recipient fit the conditions, the lender can explain the accepted option. Keep the decision with the lender’s current answer.
Refinancing with a tight deadline
A hybrid option may appear attractive when timing matters. Ask about lender acceptance, report age, acceptance review and fallback planning before you rely on it. Speed alone does not decide file fit.
Questions you may have
Is a desktop valuation the same as a hybrid valuation? NHG’s current public explanation uses hybrid valuation for a model-supported result reviewed remotely by an appraiser. Older material may use desktop valuation, so ask which product and conditions the lender means.
Can I use a hybrid valuation for every mortgage? No single answer covers every application. Ask the lender about purpose, property, loan-to-value, report form and current acceptance.
Does hybrid mean nobody checks the home? A hybrid path does not include the same property visit as a physical valuation. The remote appraiser review and the model inputs have their own boundaries.
Is 90% a general mortgage rule? NHG public guidance describes a 90% loan-to-value boundary for listed hybrid use cases. Treat it as current context to verify with NHG and the lender, not as a personal borrowing result.
Can energy improvements use a hybrid path? NHG materials identify cases where a physical valuation is required for value after quality improvements or energy-saving measures. Ask which current condition applies before booking.
How old may a physical NHG report be? NHG’s physical-report FAQ states a maximum age of six months measured from the value date in that context. Confirm the current requirement for your file.