Property Valuation for Mortgage Refinancing in Amsterdam
Prepare a clear property valuation brief for mortgage refinancing in Amsterdam, with the lender's purpose, loan position, property records and report conditions in view.
TL;DR
Before you request a refinancing valuation, confirm four things: why the loan is changing, what loan position the lender is assessing, which property records shape the evidence and which report form the recipient accepts. NHG’s current information describes physical and certain hybrid paths for qualifying files. The lender still decides what fits the application in front of you.
- Write the refinancing decision in one sentence.
- Confirm the lender, recipient and report conditions.
- Gather loan, property, leasehold and improvement records.
- Ask what inspection and evidence the assignment needs.
- Review the report against the purpose and value date.
If the purpose, recipient or timing is still unclear, share your Amsterdam refinancing question so we can help you frame the next step. Keep passports, bank details, contracts and other private documents out of the public form.
A property valuation for refinancing starts with the lender’s question
A property valuation for mortgage refinancing in Amsterdam helps place a documented value opinion inside an existing-loan decision. Start with the lender’s purpose, the proposed loan change, the property right and the report conditions. A higher or lower figure is only one part of the conversation. Income, interest, affordability and lender policy still need their own checks.
If the assignment requires a registered professional, keep the signatory’s NRVT registration beside the recipient’s requirements before you compare the report.
Who benefits from a mortgage-refinancing valuation
The preparation fits you if you are:
- reviewing the rate or terms of an existing mortgage;
- asking whether a property value supports a loan change;
- financing stated improvement work through a mortgage adjustment;
- dealing with an apartment, leasehold right or unusual property record;
- helping an owner prepare questions for a lender or mortgage adviser.
The same Amsterdam home can produce a different report request when the loan purpose changes. The first useful question is the decision the report must support.
What to gather before you ask
Keep these details together:
- the lender or adviser’s instructions;
- the current mortgage position and proposed change;
- the requested value date and any file deadline;
- address, property type, floor area and apartment or leasehold rights;
- plans, permits and invoices for completed or planned work;
- VvE, leasehold and ownership records when they apply;
- the report form, inspection method or acceptance review condition named by the lender.
Share sensitive financial and identity documents through the channel agreed with the lender or professional. A first enquiry can usually begin with the purpose and property context.
Questions to settle with the lender
A refinancing brief begins with a defined property valuation in Amsterdam, then adds the loan purpose, value date and report recipient.
An NHG mortgage adds report, acceptance review and independence requirements to the refinancing brief.
If the file allows more than one method, compare desktop and hybrid valuation methods by data source, inspection and recipient conditions.
List the address, property type, apartment right, floor, outdoor space, parking and known changes. For an Amsterdam leasehold property, collect the contract, ground-rent information, term and buyout or conversion records when they apply. When leasehold is part of your refinancing file, compare the rights record with Amsterdam leasehold records before you send the brief.
Check the purpose, value date, property identity, rights, inspection notes, comparable evidence and conclusion. The contents of the valuation report provide a sequence for that review. Send factual corrections promptly and ask whether a changed loan purpose requires a new assignment.
If you are refinancing in Amsterdam, compare the lender’s purpose and requested report scope with the details in a mortgage valuation request before comparing providers. The valuation brief supports the lender’s file, while affordability and approval remain separate decisions.
If the loan purpose, property condition or recipient changes, ask whether the report still fits. Revisit valuation-cost scope before commissioning further work.
When refinancing calls for a new valuation
A new report may enter the file when a lender needs current evidence for an altered loan, a higher advance, a renovation plan or a change in the property’s legal or physical position. The precise trigger belongs to the lender. Ask before ordering so the document matches the recipient’s rules.
An existing report, WOZ value or online estimate can help you prepare questions. Each record has its own purpose and date. A lender may require a commissioned report or an accepted hybrid product even when you already know the municipal value.
Requirements and limits
For an NHG-backed file, NHG describes a fully validated physical report or an approved hybrid valuation as accepted ways to support market value in the situations covered by its rules. Its current material also describes a maximum six-month age condition for the report and a 90% loan-to-value boundary in qualifying hybrid situations. Check the current NHG wording and the lender’s own criteria before you rely on either example.
A valuation does not decide affordability, interest, income assessment, tax treatment, building condition or legal ownership. A mortgage adviser, tax professional, building expert or legal professional handles those parts when they arise.
Five steps for a clear refinancing brief
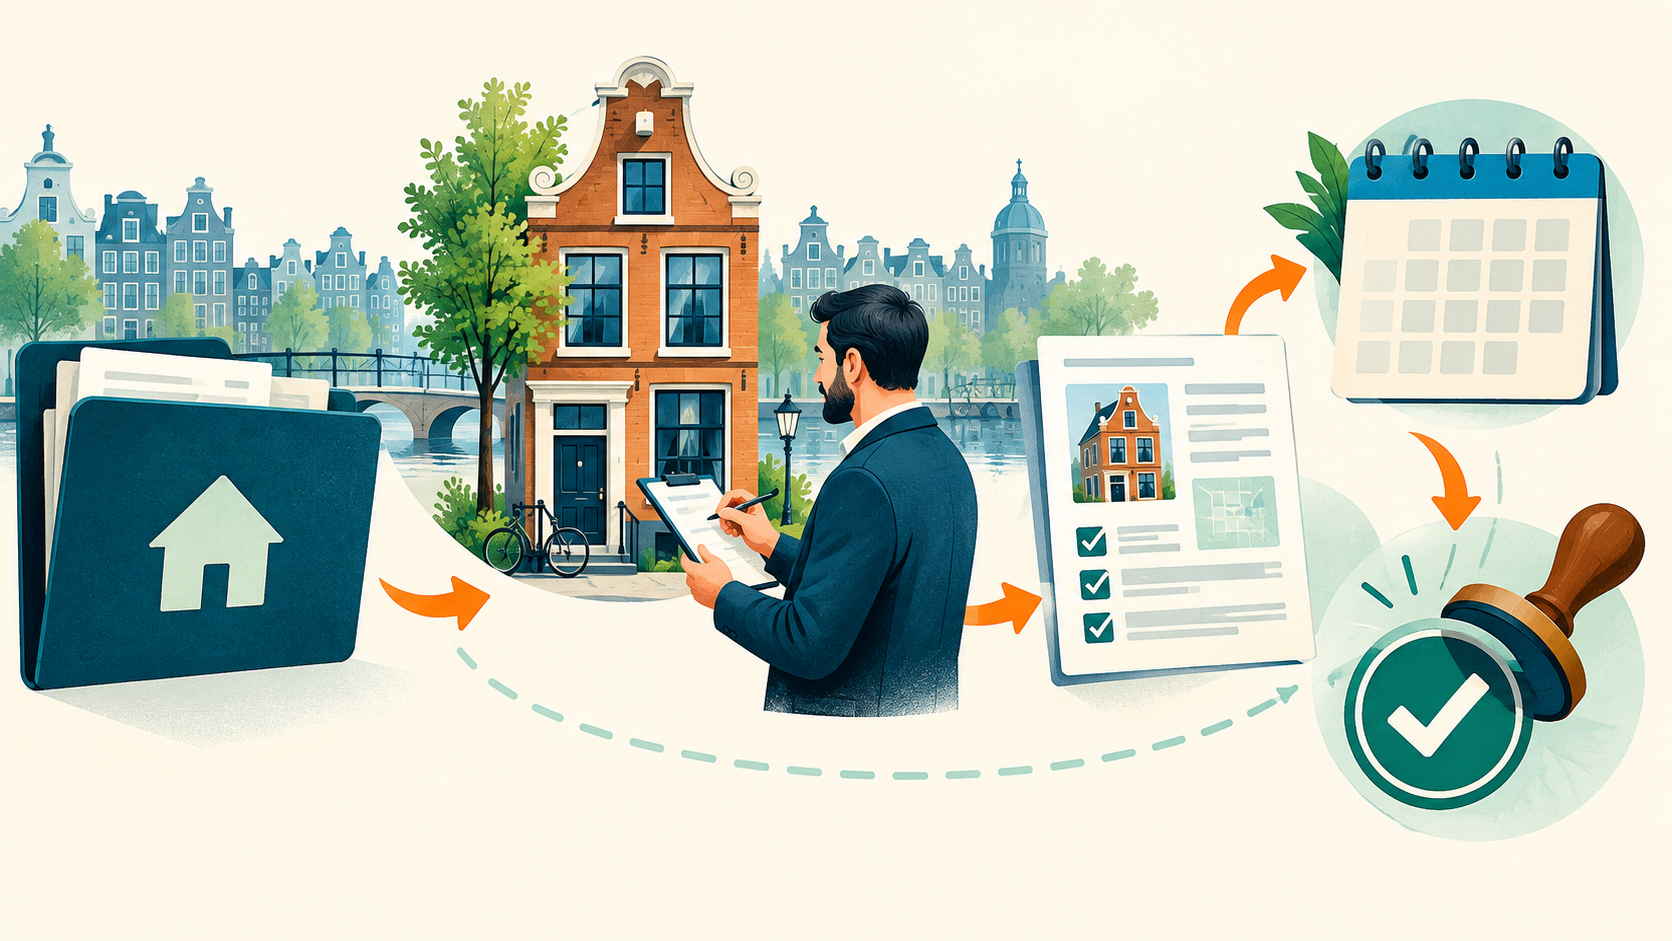
Step 1: State what is changing
Write whether you are changing the interest rate, lender, term, loan amount or an improvement budget. A short sentence such as “I am reviewing an existing mortgage and need current property evidence for the lender” gives the first conversation a usable starting point.
Step 2: Name the recipient and acceptance rule
Ask the lender which report type, inspection path, acceptance review path and value date it accepts. NHG’s rules cover defined situations, while individual lender products can add conditions. Keep the answer with the assignment records.
Step 3: Describe the property and rights
Give the appraiser the address, property type, ownership or leasehold position and any apartment records. These details tell the report which interest and property facts it must describe.
Step 4: Mark the evidence status
Separate completed work from approved work, planned work and an idea. Add drawings, permits, invoices and VvE decisions to the matching item. A report can describe an assumption, yet you and the recipient should be able to see which facts are confirmed.
Step 5: Review the delivered report
Read the report against the lender’s current instruction. Check the address, value date, rights, evidence, assumptions and recipient conditions before you rely on the conclusion.
Examples and variations
Rate review without a higher loan
The owner asks the lender whether current value evidence is needed for a rate review. The enquiry names the existing loan, property right and desired date. The lender can then decide whether a new report, a model path or another record is accepted.
Loan change with improvement work
The owner lists the current home, the proposed work and the evidence for each stage. The valuation question may need a current value, a value after described work or both. A contractor addresses construction cost and feasibility; the property appraiser addresses the assigned value question.
Apartment with leasehold records
The owner sends the apartment and VvE details together with the leasehold statement. The report request states whether the loan change relates to the current property, a ground-rent change or a completed improvement. That prevents a general refinancing request from hiding the right that affects the property.
Common mistakes and stalled files
Ordering before asking the lender: confirm the accepted report form and recipient first.
Treating a WOZ value as a lender report: use the municipal value as context and ask what the lender accepts.
Mixing current and future work: label every improvement by status and keep evidence beside it.
Leaving the value date open: ask which date anchors the loan decision and the report.
Omitting leasehold or VvE information: include the property right and building records when they affect the file.
Expecting the report to set a loan amount: keep value evidence separate from income, affordability and policy checks.
After the report is delivered
Confirm these points with the lender or adviser:
- the report type and acceptance review status;
- the property identity and rights;
- the value date and stated purpose;
- the treatment of completed or proposed work;
- any follow-up the recipient requests.
Questions you may have
Does every mortgage refinance require a new valuation? No single answer covers every lender or product. Ask the lender or adviser which evidence is accepted for the change you are considering.
Can a WOZ value replace a property valuation? A WOZ value is a municipal record with its own purpose and date. It may help with orientation, while the lender decides whether it meets the file requirement.
Can a hybrid valuation be used for refinancing? NHG describes hybrid paths for qualifying refinancing situations, with conditions such as accepted products and a loan-to-value boundary. Confirm the current rule and the lender’s product conditions before you order.
What if the home has leasehold? Include the leasehold contract, ground-rent details and any buyout or conversion record that applies. Ask whether the lender needs a value question tied to the current right or a change to it.
Should planned improvements be included? State what is completed, approved, planned and uncertain. The assignment determines whether the value question concerns the present home, a described future state or both.
Does a higher value guarantee better terms? No. A value opinion is one input; the lender also checks income, debts, product rules and the complete application.
Documents and useful questions
Before you send the enquiry, prepare:
- lender instructions and the name of the recipient;
- the existing loan purpose and proposed change;
- property, apartment and leasehold records;
- VvE documents and improvement evidence when relevant;
- the value date, deadline and questions about report acceptance.
The report should answer the assigned question, while your mortgage adviser can explain the wider financial decision.